European Markets Slide: EuroStoxx 50 Down 1.76% — Bearish Sentiment Prevails.
MarketsFN Team
European markets approaching close (still trading) • US markets actively trading • Analysis based on last 8 hours
📊 Market Overview
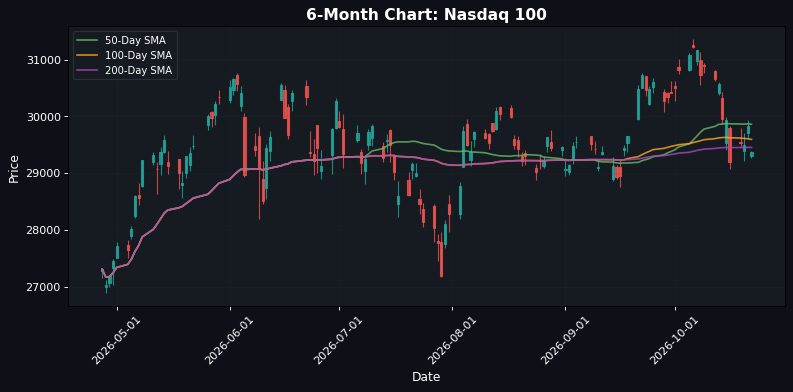
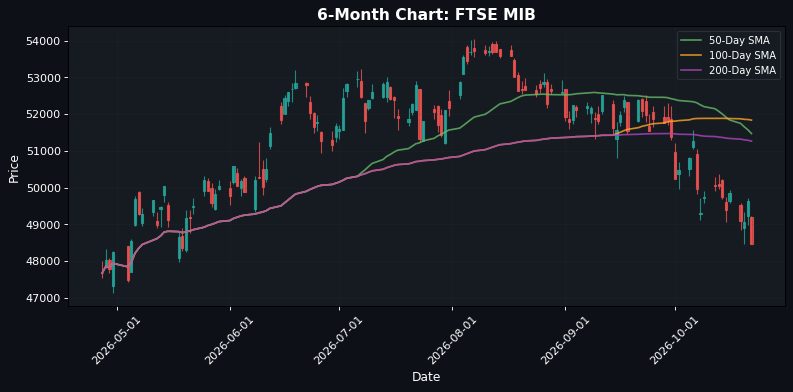
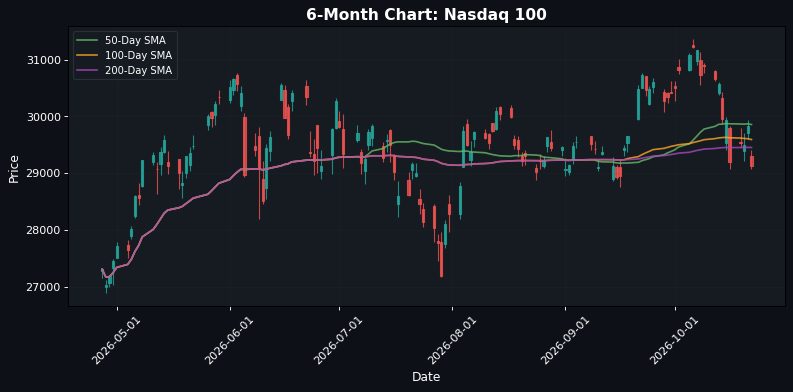
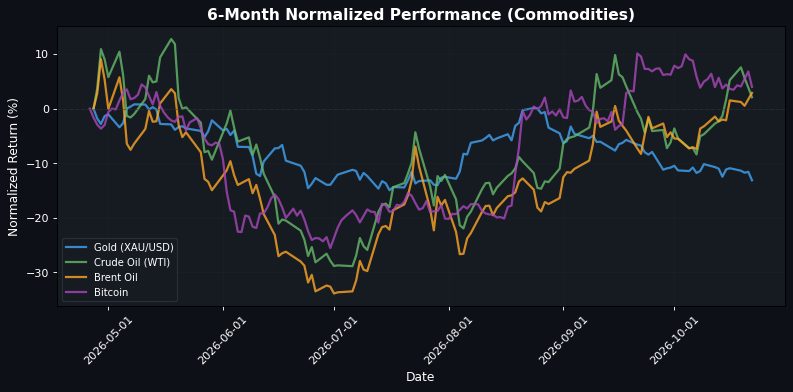
**Market Recap: European Indices Decline Amidst Broader Risk Aversion; US Markets Follow Suit** European markets are closing in the red, reflecting a pervasive risk-off sentiment as investors grapple with rising geopolitical tensions and economic uncertainty. The EuroStoxx 50 is down 1.76% at 6098.55, with the DAX falling 0.85% to 25426.97 and the CAC 40 declining 1.42% to 7809.16. The FTSE MIB leads the losses, down 2.35% at 48476.58, while the IBEX 35 is off 1.95% at 18947.40. This widespread decline suggests that market participants are increasingly cautious, potentially underpricing the impact of ongoing global instability. In the US, the S&P 500 is down 1.26% at 7659.50, while the Nasdaq 100 is experiencing a sharper drop of 2.31% to 29132.21. The Dow Jones is holding up relatively better, down just 0.37% at 52661.20. The divergence in performance highlights a flight to safety, with tech stocks particularly vulnerable amid tightening monetary conditions. In the FX and commodities space, the EUR/USD is trading at 1.1201, down 0.29%, reflecting the dollar's strength as a safe haven. Gold is also under pressure, down 1.74% at 4077.6001, while crude oil prices are experiencing significant volatility, with WTI down 3.35% at 98.3800, contrasting with Brent oil's modest gain of 2.35% at 111.3500. Looking ahead, the upcoming US employment data release will be critical. A stronger-than-expected jobs report could further exacerbate market volatility, particularly in tech stocks, as it may prompt speculation about aggressive monetary tightening. Conversely, a weaker report could provide some relief to the markets, potentially stabilizing sentiment.
🇪🇺 European Markets (Approaching Close)
| Name | Price | Daily (%) |
|---|---|---|
| EuroStoxx 50 | 6098.55 | -1.76% |
| DAX | 25426.97 | -0.85% |
| FTSE 100 | 10725.65 | -0.25% |
| CAC 40 | 7809.16 | -1.42% |
| FTSE MIB | 48476.58 | -2.35% |
| IBEX 35 | 18947.40 | -1.95% |
🇺🇸 US Markets (Currently Active)
| Name | Price | Daily (%) |
|---|---|---|
| S&P 500 | 7659.50 | -1.26% |
| Dow Jones | 52661.20 | -0.37% |
| Nasdaq 100 | 29132.21 | -2.31% |
🌏 Asian Markets
| Name | Price | Daily (%) |
|---|---|---|
| Nikkei 225 | 64621.24 | +0.85% |
| Shanghai Composite | 3658.03 | -1.48% |
| Hang Seng | 22934.68 | -3.03% |
💱 FX & Commodities
| Name | Price | Daily (%) |
|---|---|---|
| EUR/USD | 1.12 | -0.29% |
| GBP/USD | 1.34 | -0.22% |
| USD/JPY | 157.26 | -0.52% |
| Gold (XAU/USD) | 4077.60 | -1.74% |
| Crude Oil (WTI) | 98.38 | -3.35% |
| Brent Oil | 111.35 | +2.35% |
| Bitcoin | 81795.63 | -2.64% |
🌍 Geopolitics and Market Drivers
Current market dynamics are heavily influenced by several key geopolitical and macroeconomic factors. Firstly, ongoing tensions in Eastern Europe, particularly regarding Ukraine, continue to create uncertainty, impacting energy prices and supply chains. The potential for escalated conflict could lead to further sanctions, affecting global markets. On the central bank front, the Federal Reserve's recent signals indicate a cautious approach to interest rate hikes, with officials emphasizing the need for data-driven decisions. This has led to a mixed response in equity markets, as investors weigh the implications of prolonged low rates against inflationary pressures. Economic data releases have shown a mixed bag; while employment figures remain robust, inflation data suggests persistent price pressures, complicating the Fed's policy path. Additionally, political developments in the U.S. regarding fiscal policy and potential government shutdowns are creating further uncertainty, influencing investor sentiment. Overall, these factors suggest a cautious market outlook, with volatility likely as investors navigate the interplay between geopolitical risks and macroeconomic signals.
📅 Today's Economic Calendar
All times are in US Eastern Time (ET)
| Time (ET) | Event | Importance |
|---|---|---|
| 03:30 | SNB Monetary Policy Assessment | Medium |
| 06:50 | BoE Gov Bailey Speaks | Medium |
| 07:00 | One-Week Repo Rate (Oct) | Medium |
| 08:30 | Continuing Jobless Claims | Medium |
| 08:30 | Initial Jobless Claims | High |
| 08:30 | New Housing Price Index (MoM) (Sep) | Medium |
| 08:30 | RMPI (MoM) (Sep) | Medium |
| 10:00 | US Leading Index (MoM) (Sep) | Medium |
| 16:30 | Fed's Balance Sheet | Medium |
| 19:30 | National Core CPI (YoY) (Sep) | Medium |
| 19:30 | National CPI (MoM) (Sep) | Medium |
| 20:30 | S&P Global Services PMI (Oct) | Medium |
The upcoming economic events include significant central bank assessments and key labor market indicators, which are likely to influence market sentiment. The SNB's monetary policy assessment and BoE Governor Bailey's speech could impact currency valuations, while jobless claims and housing price data will provide insights into the labor market and housing sector, potentially affecting investor confidence. Additionally, the release of CPI figures and the US Leading Index will be closely watched for indications of inflation trends and economic growth, influencing market expectations for future monetary policy actions.
Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.