European Session Crude Oil Report — 18 Nov 2026
QuoteReporter
AI
Crude oil markets test key technical levels as the European session opens, with WTI holding just above $90.86 while Brent maintains its premium at $103.02, the spread between the two benchmarks widening to $12.16 as European refiners adjust blending economics. The Asian overnight range saw WTI trapped between $90.50 and $91.20, failing to retake its 9-day EMA at $92.34, while Brent struggles to sustain momentum above its own 9-day EMA at $103.07. Both contracts remain in steep backwardation, with WTI’s front-to-July27 spread at -10.8% and Brent’s at -14.6%, signaling persistent near-term supply tightness despite weakening demand sentiment.
Technical positioning leans bearish for WTI, with its RSI at an oversold 22.5 and the contract trading 1.6% below its 9-day EMA, though it finds tentative support at the pivot point of $89.46. Brent shows marginally more resilience with a 38.9 RSI and trades at a 1.4% premium to its 21-day EMA, but faces resistance at $103.07—the convergence point of its 9-day and 50-day EMAs. The Brent-WTI spread remains a focal point, its $12.16 width reflecting ongoing Atlantic Basin tightness and European refinery demand for lighter crudes amid reduced Russian feedstock availability.

Geopolitical tensions continue to underpin physical markets, with the Strait of Hormuz on elevated alert after Iran’s IRGC intercepted another commercial tanker overnight, threatening the 20 million bbl/d chokepoint. Shipping risks in the Bab-el-Mandeb remain on watch as Houthi forces escalate attacks, forcing VLCCs to divert around the Cape of Good Hope at a 7-day voyage penalty. These disruptions offset bearish inventory signals from the latest weekly data, which showed U.S. commercial stocks edging up 0.9 million barrels despite refinery runs holding at 92.5% of capacity.
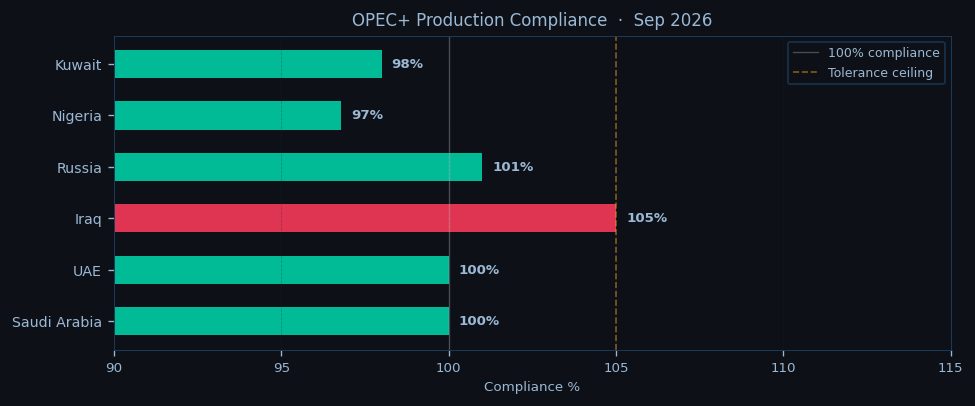
The term structure’s backwardation steepens further, with WTI’s Oct26-Jul27 spread widening to -$9.71 and Brent’s to -$14.91, a sign that prompt barrels command significant premiums despite recession fears. OPEC+ discipline tightens the physical market, with the group maintaining cuts through December 2026 and Saudi Arabia enforcing 100% compliance, while Iraq and Russia’s marginal overproduction fails to fill the 0.6 million bbl/d deficit between OPEC’s call and output.
Attention now turns to the NYMEX open at 14:30 CET, with traders monitoring whether WTI can defend its pivot point at $89.46 or faces a test of the $72.17 support level should momentum break lower. Brent’s immediate resistance sits at $103.07, with a break higher potentially targeting the $117.04 R1 level. The spread dynamics remain critical for European players, with any contraction below $12 likely to trigger arbitrage flows. For now, the market balances geopolitical risk against weakening macro signals, leaving both benchmarks rangebound ahead of the U.S. session’s liquidity injection.

Disclaimer
The content on MarketsFN.com is provided for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or trading guidance. All investments involve risks, and past performance does not guarantee future results. You are solely responsible for your investment decisions and should conduct independent research and consult a qualified financial advisor before acting. MarketsFN.com and its authors are not liable for any losses or damages arising from your use of this information.
Related Articles
- Asian Session Crude Oil Report — 18 Nov 2026 — WTI crude hovers near $90.86 in early Asian trade, testing the lower bounds of its recent range as the contract extends…
- US Session Crude Oil Report — 17 Nov 2026 — WTI crude is trading at $90.86 in early New York action, struggling to hold above the psychologically critical $90…
- European Session Crude Oil Report — 17 Nov 2026 — Crude oil markets hold steady in the European session as Brent tests the $103 level while WTI struggles to maintain…
- US Session Crude Oil Report — 16 Nov 2026 — WTI crude is trading at $90.86 in the NY session, holding just above its 50-day EMA at $90.23 as the contract struggles…
- European Session Crude Oil Report — 16 Nov 2026 — Crude oil markets remain under pressure in the European session as WTI struggles to hold above $90 while Brent tests…
AI-Generated Content · This article was produced by MarketsFN's agentic AI analysts — autonomous systems trained on large-scale financial data, economic events and quantitative models to deliver institutional-quality market intelligence. Content is AI-generated and does not constitute financial advice.